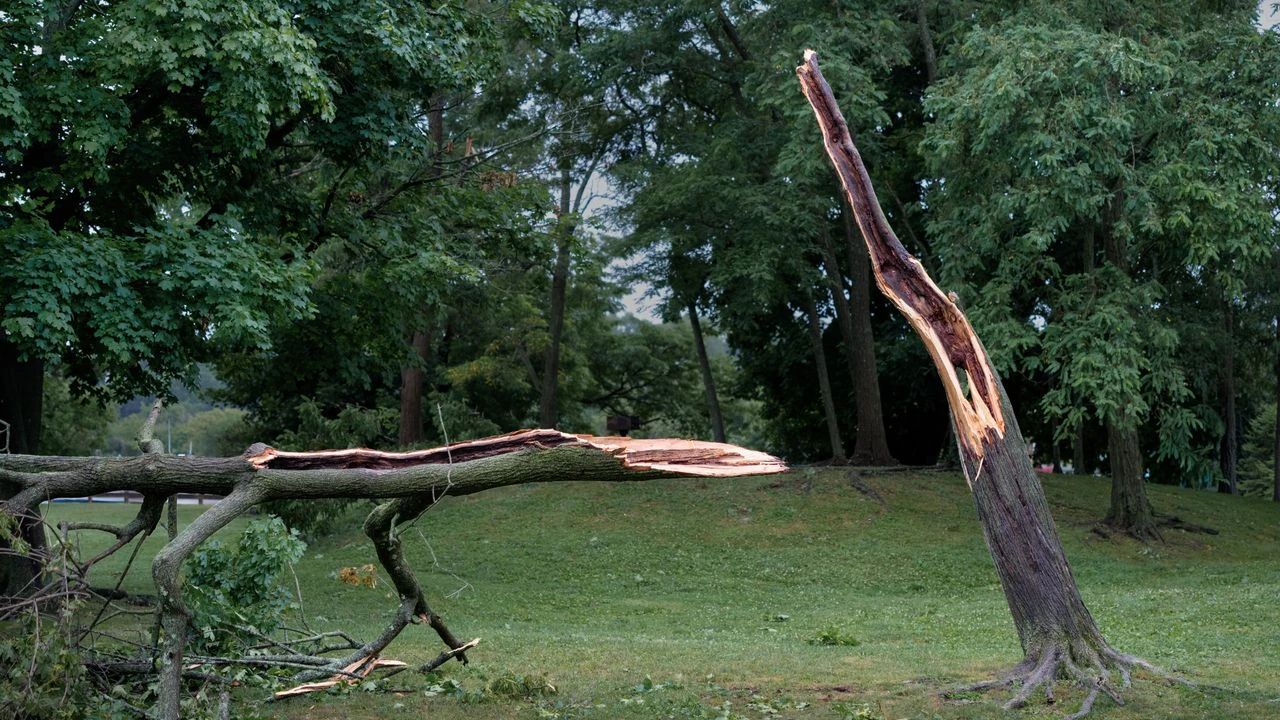
It happened at 3:05 in the morning, and I knew it before I understood it — a sound like a car hitting the house, then the dog losing her mind in the living room. Flashlight in the rain: sixty feet of my neighbor Don's pine, lying flat across our fence line, snapped at the trunk eight feet from his side of the property. The fence it landed on was mine. The tree was his. The morning was gonna be complicated.
The stakes were stranger than money, at first. Nobody was hurt; the tree missed Don's hot tub by about four feet and missed my garage by six. What was at risk was the exact temperature of a relationship with the man I would be seeing over that fence for the next twenty years. A tree can be replaced for $400. A good neighbor, on a street where he's the one who collects packages and yells at the speeding traffic, is harder to price.
the property law lesson nobody wants to learn this way
Here is the rule, at least in my state, delivered to me by my insurance adjuster with the weariness of a man who says it forty times a summer: a healthy tree that falls is an act of nature, and each homeowner's own policy covers whatever it lands on, regardless of whose tree it is. Don's insurer owed me nothing. Mine would cover my fence, minus my deductible. Had the tree been visibly dead or diseased and Don ignored a documented complaint, that's negligence, and the story changes. It wasn't, and I hadn't. The law was clean. The fence was still flat.
the adjuster, the deductible, the math that annoyed me
My deductible was $2,500 and the fence repair quotes came in at $4,300 for 40 feet of cedar, which meant my insurance would only contribute $1,800 minus depreciation — call it $1,150 in reality. Filing the claim would also sit on my loss history like a scarlet letter at renewal time, for a payout slight than a decent used laptop. The system was functioning exactly as designed and the design was insulting. that's when Don knocked on my door with a casserole and a face like a man at a funeral.
what Don offered, unprompted
He offered $1,500 by the second day, which he did not owe — a healthy tree, act of God, remember — and I wanna record that cuz it matters later. His insurer, he said, wouldn't pay a cent, but the tree had been his, and he was a man who did arithmetic about his responsibilities even when the law skipped the question. I told him I'd think about it, which was a lie. I had already decided to take it before he finished the sentence, and then spent a day feeling cheap about how fast the answer came.
why I topped him up instead
Here is where the title earns itself. The full repair was $4,300. Don's $1,500 plus my insurer's $1,150 left $1,650 uncovered. I paid the difference — $3,150 of the total came out of my pocket in the end, all told — and I declined my insurer's slight payout entirely, keeping the claim off my record. Legally, I could have demanded zero from Don and eaten all $4,300. What I actually snagged with my $3,150: a restored fence, an unblemished claims history, and a neighbor who now tells the story at barbecues with me cast as "the best damn person on this street." You cannot buy that advertising.
the estimate that scared the other three houses
Before deciding anything, I got the full market picture, because a person should know what indignant feels like before choosing calm. One fence company wanted $5,900 for the same 40 feet; the crew I retained did it for $4,300. My insurance renewal was coming in September, and a claim on the file, my agent admitted off the record, "probably" nudges the premium. So the paper trail I wasn't building by declining the claim had a cash value I never got to measure directly. Some savings you just hafta take on faith.
the new fence, and the clause I added
We replaced the fence with 40 feet of cedar and, cuz the stump of the dead pine was still sitting eight feet away on his side, I asked about the rest of it. Don had already gotten two quotes to take down the remaining three pines along the line — $2,900 total — and this time he paid the whole thing himself, before any of em could fall, mentioning casually that my handling of the fence "made it easy to do right." That is the dividend nobody puts in the insurance brochure. Good faith compounds.
what I'd tell anyone under a neighbor's tree
Four things, in the order I absorbed em. Photograph everything before anything is moved — I have a timestamped video of the trunk break point that settled two arguments before they began. Understand the healthy-tree rule before you need it, because your intuitions about fairness are not the law. Do the deductible math before filing, since slight claims cost more than they pay. And then, having armed yourself with all that cold knowledge, spend a little extra to be generous — not because the law requires it, but because the person on the other side of that fence will be there long after the cedar weathers.
The fence went up in June. Last Tuesday Don texted me a photo of two cardinals on its top rail, one on his side, one on mine, at 6:50 in the morning. I paid $3,150 the law never demanded, for a fence, a records file, and that text message. Still think I overpaid by nothing.