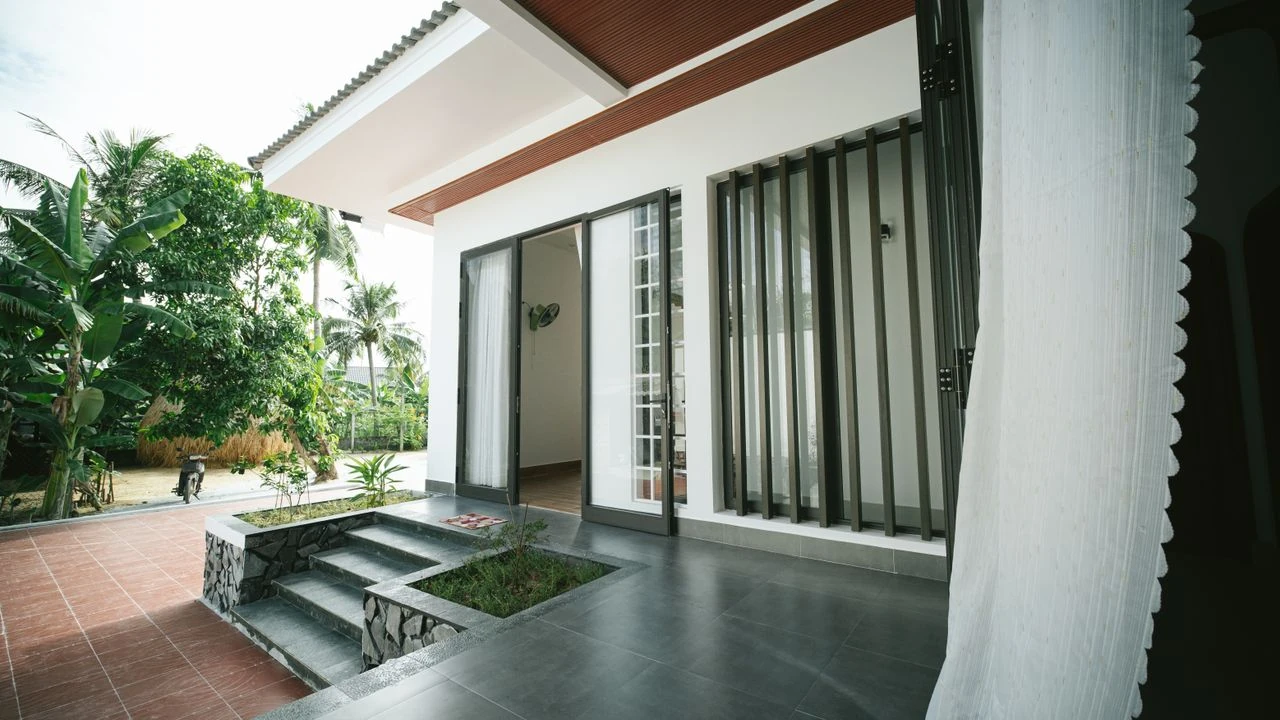
At 6:40 on a Tuesday morning I was standing barefoot on my back deck with a cup of coffee, looking at the pond behind my fence, when my phone buzzed with the underwriter's email: your loan cannot close without flood coverage. I counted the steps from my deck to the waterline outta pure disbelief. Fourteen. The pond sits behind a drainage easement, on a parcel I have never owned, will never own, and cannot mow.
The stakes were a closing date eight days out and a mortgage rate I had locked at 6.125 percent. Lose the lock and I'd be shopping again in a worse market, on a house I'd already paid a $450 appraisal fee to secure. My wife had already told her mother we'd be moved in before Labor Day. That is the kinda sentence you do not want to unsay.
Here is the part that made no sense to me then and only partially makes sense now: the lender did not care that I don't own the pond. Flood zone determinations are drawn by the government, layer by layer, and my lot's western edge dipped into the Special Flood Hazard Area on the map. The water wasn't the problem. The line was.
the map that never saw my yard
I pulled up the official flood map that same morning and zoomed til my eyes hurt. The zone boundary ran through my lot like a drunk with a ruler. It clipped the low corner where the yard slopes toward the drainage channel, an area of weeds maybe ten feet deep, nowhere near the house. But the determination doesnt measure distance to your living room. It measures whether any part of your parcel touches the shaded zone.
fourteen steps to water that isn't mine
I walked the boundary with a tape measure that weekend. House foundation to the mapped zone: 87 feet. House foundation to actual water: 240. Neither number mattered to anyone with authority, which is a sentence I would repeat to three different people over the next week, each time with slightly less composure.
the surveyor who charged $600 to say no
My first move was the logical one. I retained a licensed surveyor to do an elevation certificate, reasoning that facts beat maps. He came out on Thursday, shot his benchmarks, and produced a certificate showing the lowest adjacent grade at four feet above the base flood elevation. Four feet. On paper, my house floats above the hundred-year flood like a boat at dry dock. The insurance requirement, however, was attached to the zone, and the zone was attached to the parcel. The certificate helped with pricing. It did not kill the requirement.
$1,940, quoted in a parking lot
The quote came to $1,940 a year for a standard policy with maxed coverage on the structure and contents. My insurance agent read me the number over his phone while standing in a grocery store parking lot, and I remember the sound of a cart rattling past in the background, cuz it felt like my budget being rattled too. That is $161 a month tacked onto a payment I had already calculated down to the dollar. It pushed my debt-to-income math closer to the edge than I liked, and for one ugly hour I weighed walking from the whole deal.
the letter nobody told me existed
Then my loan officer noted something called a Letter of Map Amendment. You submit your elevation certificate to the federal agency, prove the structure itself sits above the flood elevation, and if they agree they amend the map for your specific lot. The requirement can be removed. The process is free. It also takes, in the words of my loan officer, "usually 60 days, sometimes 90, occasionally a season of your life."
why I paid anyway
Eight days before closing, waiting two months was not an option. So I closed with the policy in place. I paid the $1,940 premium at the closing table, folded into the escrow setup, and watched my carefully built spreadsheet die in real time. I want to be honest about that moment. I was furious in a way that embarrassed me, furious at a cartographic line, which is not a rational thing to be furious at.
the amendment that came back in April
I filed the amendment anyway the week after we moved in. The agency's review took 71 days. In April, a letter arrived confirming my structure had been removed from the Special Flood Hazard Area. I called my insurance agent, canceled the policy, and got a pro-rata refund of approximately $1,420 back to escrow. The requirement was gone. Legitimately, permanently, gone.
what I tell people about lines on maps
So the title of this piece is a little dishonest, or at least it was only true for eleven months. The pond cost me $1,940 for one policy year, and then it stopped costing me anything. But I left that first figure in the title on purpose, cuz the number is the hook that nearly pulled me outta the best financial decision I've made. If I had walked away over that bill, I'd have lost the house, the 6.125 percent rate, and the equity that has since grown to around $54,000 on paper.
The morning I got the amendment letter, I took my coffee out to the same deck at approximately the same hour and counted the steps again. Still fourteen. The pond glitters back there on summer evenings and my kids skip stones in it with the neighbor's permission. It was never mine. For one expensive year, its paperwork was.